Consumer Commission Orders Chit Company to Repay Defrauded Bengaluru Investor
A Bengaluru resident who paid monthly installments for a five‑lakh rupee chit scheme received only twenty thousand rupees, prompting the consumer commission to order repayment of over four lakh rupees with interest. The ruling underscores growing scrutiny of informal savings mechanisms.
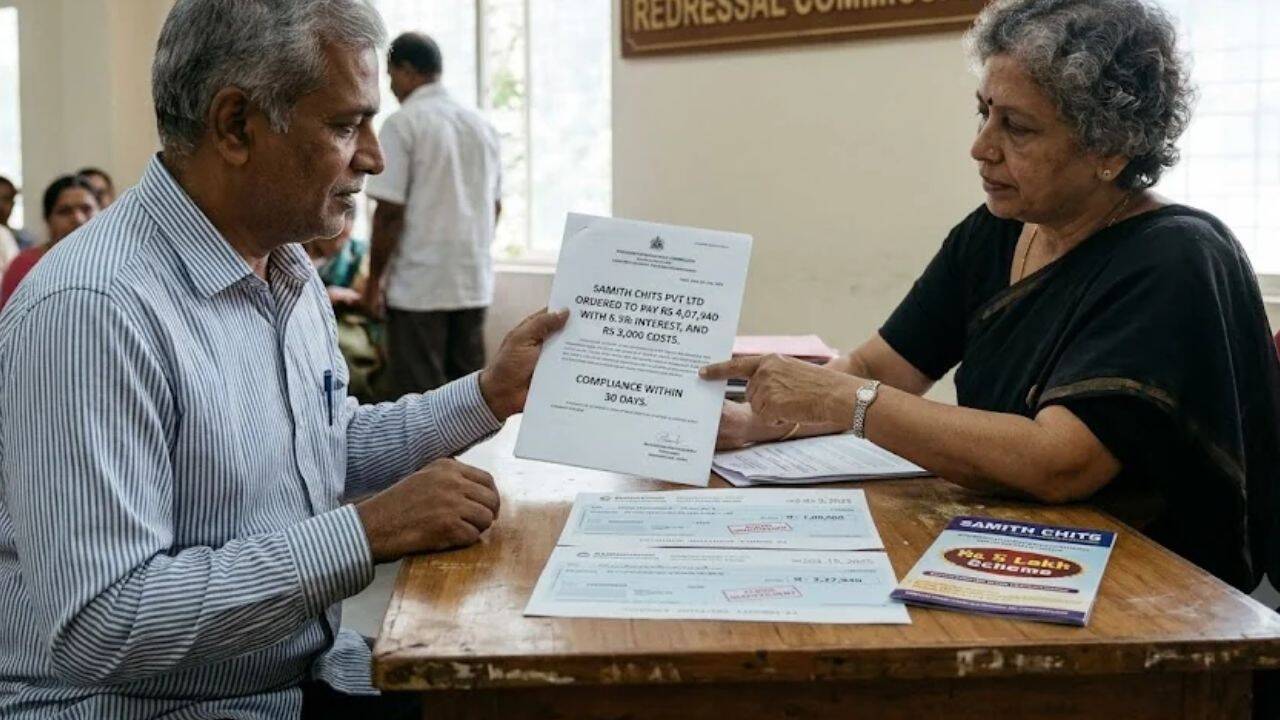
The concrete rupture unfolded when the Karnataka State Consumer Disputes Redressal Commission delivered its verdict against a chit‑fund operator accused of misappropriating payments from a Bengaluru subscriber. The plaintiff, who contributed twelve thousand five hundred rupees each month for over three years, was left with a paltry return of twenty thousand rupees, a stark contrast to the promised five‑lakh payout. The commission mandated the company to reimburse the investor four lakh seven thousand rupees, plus statutory interest, marking a decisive legal rebuke of the scheme's practices.
Underlying tension lies in the broader ecosystem of informal credit and savings arrangements that thrive in urban and semi‑urban India. While chit funds have historically provided accessible financing for many, lax regulatory oversight has allowed unscrupulous operators to exploit participants. Consumer advocates argue that the case reflects systemic gaps in enforcement, prompting calls for tighter licensing requirements and real‑time monitoring of fund flows. The commission's decision may embolden other aggrieved investors to seek redress, potentially overburdening an already stretched adjudicatory system.
Downstream consequences include heightened awareness among potential investors about the risks inherent in unregistered financial products. Financial institutions may experience a modest shift as consumers gravitate toward formal banking channels perceived as safer. Moreover, the ruling could stimulate legislative initiatives aimed at tightening the legal framework governing chit funds, thereby altering the market dynamics for informal savings instruments across Karnataka and beyond.
Comments 0