Economic Indicators and Skirt Lengths Re-examined Through the Prism of Financial Folklore
Financial analysts are revisiting the unconventional hemline index to gauge consumer confidence and broader macroeconomic trends. The theory posits a direct correlation between skirt lengths and equity market cycles.
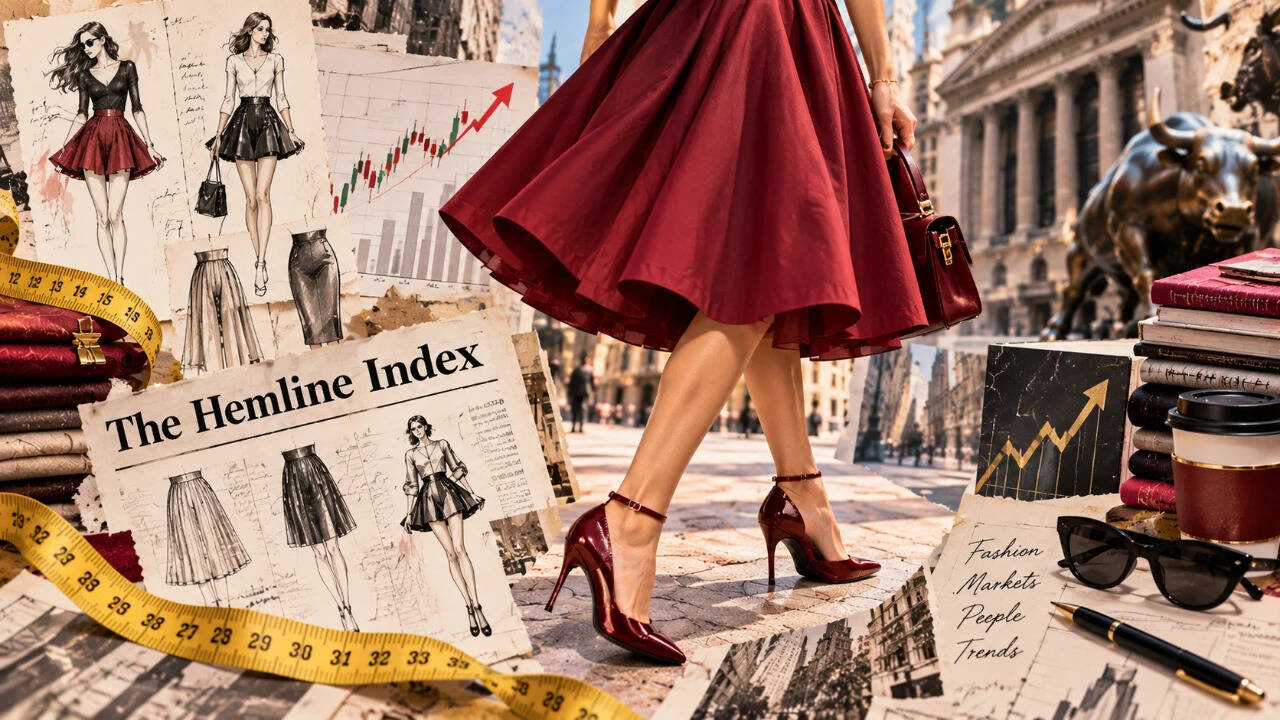
As global markets navigate persistent inflationary pressures and monetary policy shifts, commentators have resurrected quirky alternative economic indicators. The hemline hypothesis suggests that during bull markets, rising optimism translates into shorter hemlines, whereas economic downturns prompt conservative, longer attire. While modern economists dismiss the metric as financial folklore, it endures as a popular heuristic for consumer sentiment and societal risk appetite. The persistence of such folklore highlights the psychological dimensions of modern financial markets, which remain driven by behavioral quirks alongside quantitative modeling. Institutional investors rely on sophisticated algorithms, yet retail participants frequently seek intuitive physical metaphors to make sense of macro volatility. This disconnect between academic finance and popular economic theory demonstrates the human desire for simple patterns in complex systems. The immediate consequence is harmless amusement, yet it underscores the ongoing search for leading indicators in unpredictable financial climates. Market participants ultimately rely on hard earnings data and central bank liquidity rather than apparel metrics. Nevertheless, the enduring appeal of the index reveals how deeply human psychology influences economic observation.
Comments 0