Tribunal rejects fine only for filing I-T return after notice
A tax tribunal in Mumbai dismissed a fine that was imposed solely for filing an income‑tax return after a notice was issued. The ruling clarifies the limits of penalties for procedural lapses.
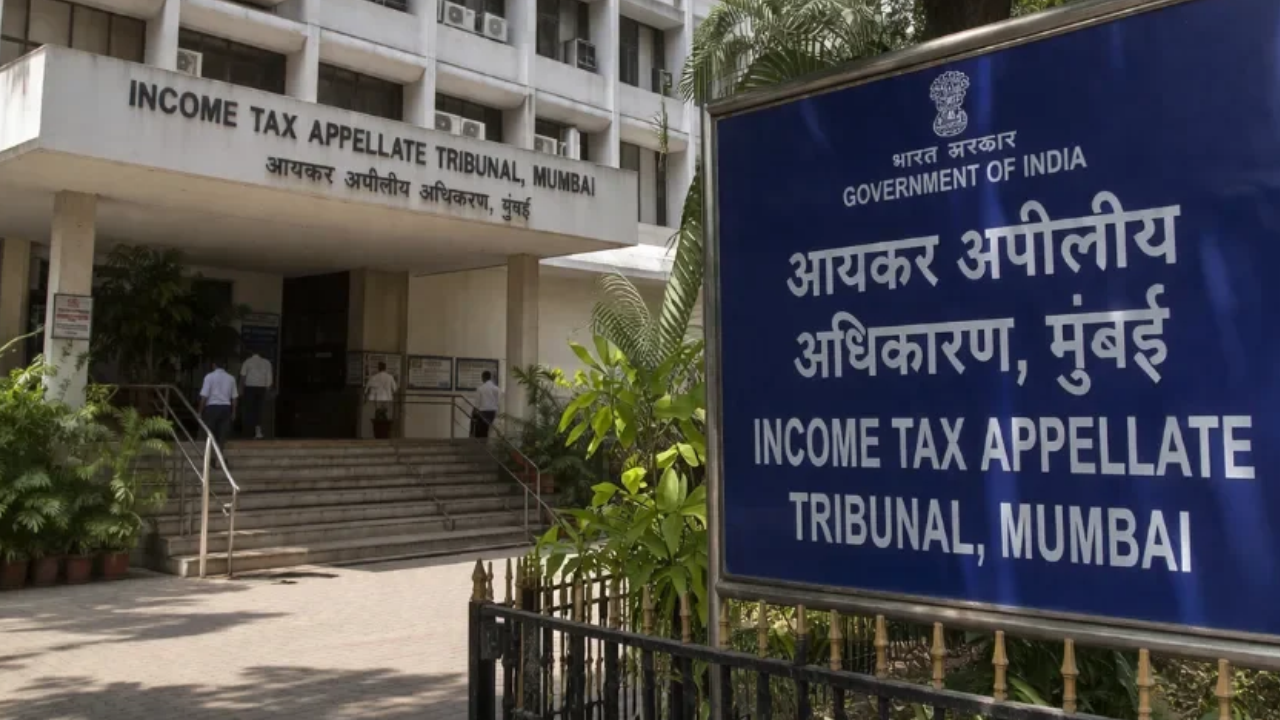
The Income Tax Department had issued a notice to a taxpayer in Mumbai for filing a return after the prescribed deadline, and subsequently levied a fine that was limited to the act of filing itself. The taxpayer appealed the penalty, arguing that the fine did not reflect any actual loss of revenue and that the department had not followed due process in issuing the notice. The case was taken to the Maharashtra Tax Tribunal for a final decision.
The tribunal examined the provisions of the Income Tax Act and found that a fine can only be imposed when there is a clear breach of statutory duty that results in a quantifiable loss or when the taxpayer has willfully evaded tax. In this instance, the only alleged breach was the timing of the return, which the tribunal deemed insufficient grounds for a monetary penalty. The judges therefore set aside the fine and directed the department to refund any amount that had already been collected.
The decision has implications for millions of taxpayers across Maharashtra who may face similar notices for delayed filings. It reinforces the principle that penalties must be proportionate to the nature of the violation and that administrative actions must be transparent. For readers in the state, the ruling offers reassurance that the tax system can be challenged in court and that undue financial burdens can be contested.
Comments 0